Funding & finance
Understanding federal tax support for business heat pumps
How eligible heat-pump investments can benefit from tax credits, and why deductions must be evaluated separately.
Adapted for PB Energy’s Insights archive from David Brushett’s LinkedIn commentary. The date shown is the original post date. Tax wording reviewed in September 2026.
Federal tax measures can change the business case for replacing fossil-fuel heating with eligible heat pumps. The opportunity is especially relevant when existing equipment is approaching the end of its life and replacement spending is already required.
A refundable investment tax credit
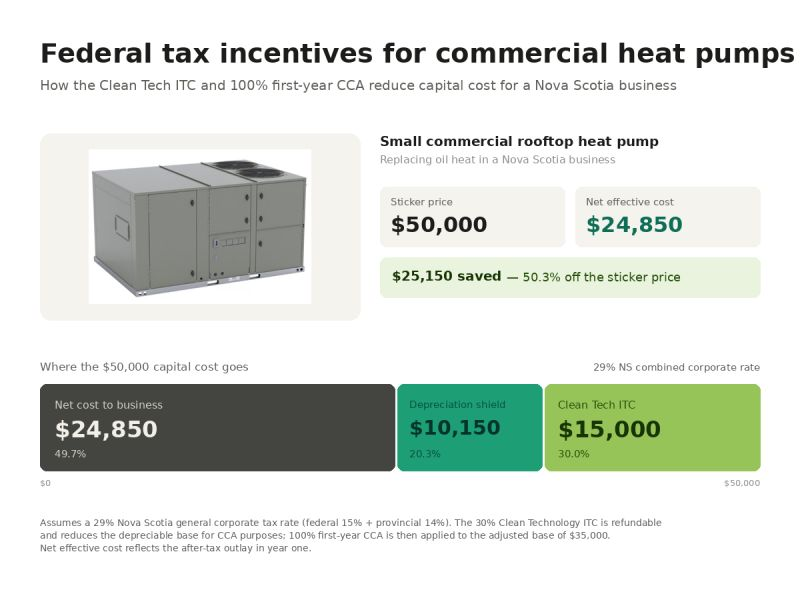
The federal Clean Technology Investment Tax Credit is refundable and can provide up to 30% of eligible capital costs, subject to its requirements. Qualifying property can include eligible air-source and ground-source heat pumps. Not every owner or installation qualifies; claimant eligibility, equipment, timing and labour requirements affect the assessment.
A deduction is different from a credit
Capital cost allowance reduces taxable income. Its financial value depends on the applicable tax rate and when deductions can be used. Accelerated depreciation affects the timing of deductions; it is not an additional rebate equal to the equipment cost.
The original post discussed Budget 2025 and combined tax benefits. A blanket claim that incentives reduce every project’s capital cost by more than half would be misleading. Any calculation needs to account for the eligible cost base, adjustments for assistance and tax credits, applicable depreciation rules and the business’s circumstances.
Build a project-specific comparison
Compare the after-tax cost and expected operating costs of suitable alternatives, including electrical upgrades and building improvements. Confirm the tax treatment with the project’s tax adviser before relying on it in a capital decision.
CRA guidance on the Clean Technology ITC: https://www.canada.ca/en/revenue-agency/services/tax/businesses/topics/corporations/business-tax-credits/clean-economy-itc/clean-technology-itc/about-ct-itc.html (opens in a new tab)
CRA guidance on qualifying property: https://www.canada.ca/en/revenue-agency/services/tax/businesses/topics/corporations/business-tax-credits/clean-economy-itc/clean-technology-itc/property-qualifies-ct-itc.html (opens in a new tab)